GloBE as a Regular Corporate Income Tax System: Tax Base and Subject by Professor Peter Harris
4 September 2026
Is GloBE simply a set of global minimum tax rules—or should it be understood as a corporate income tax system in its own right?
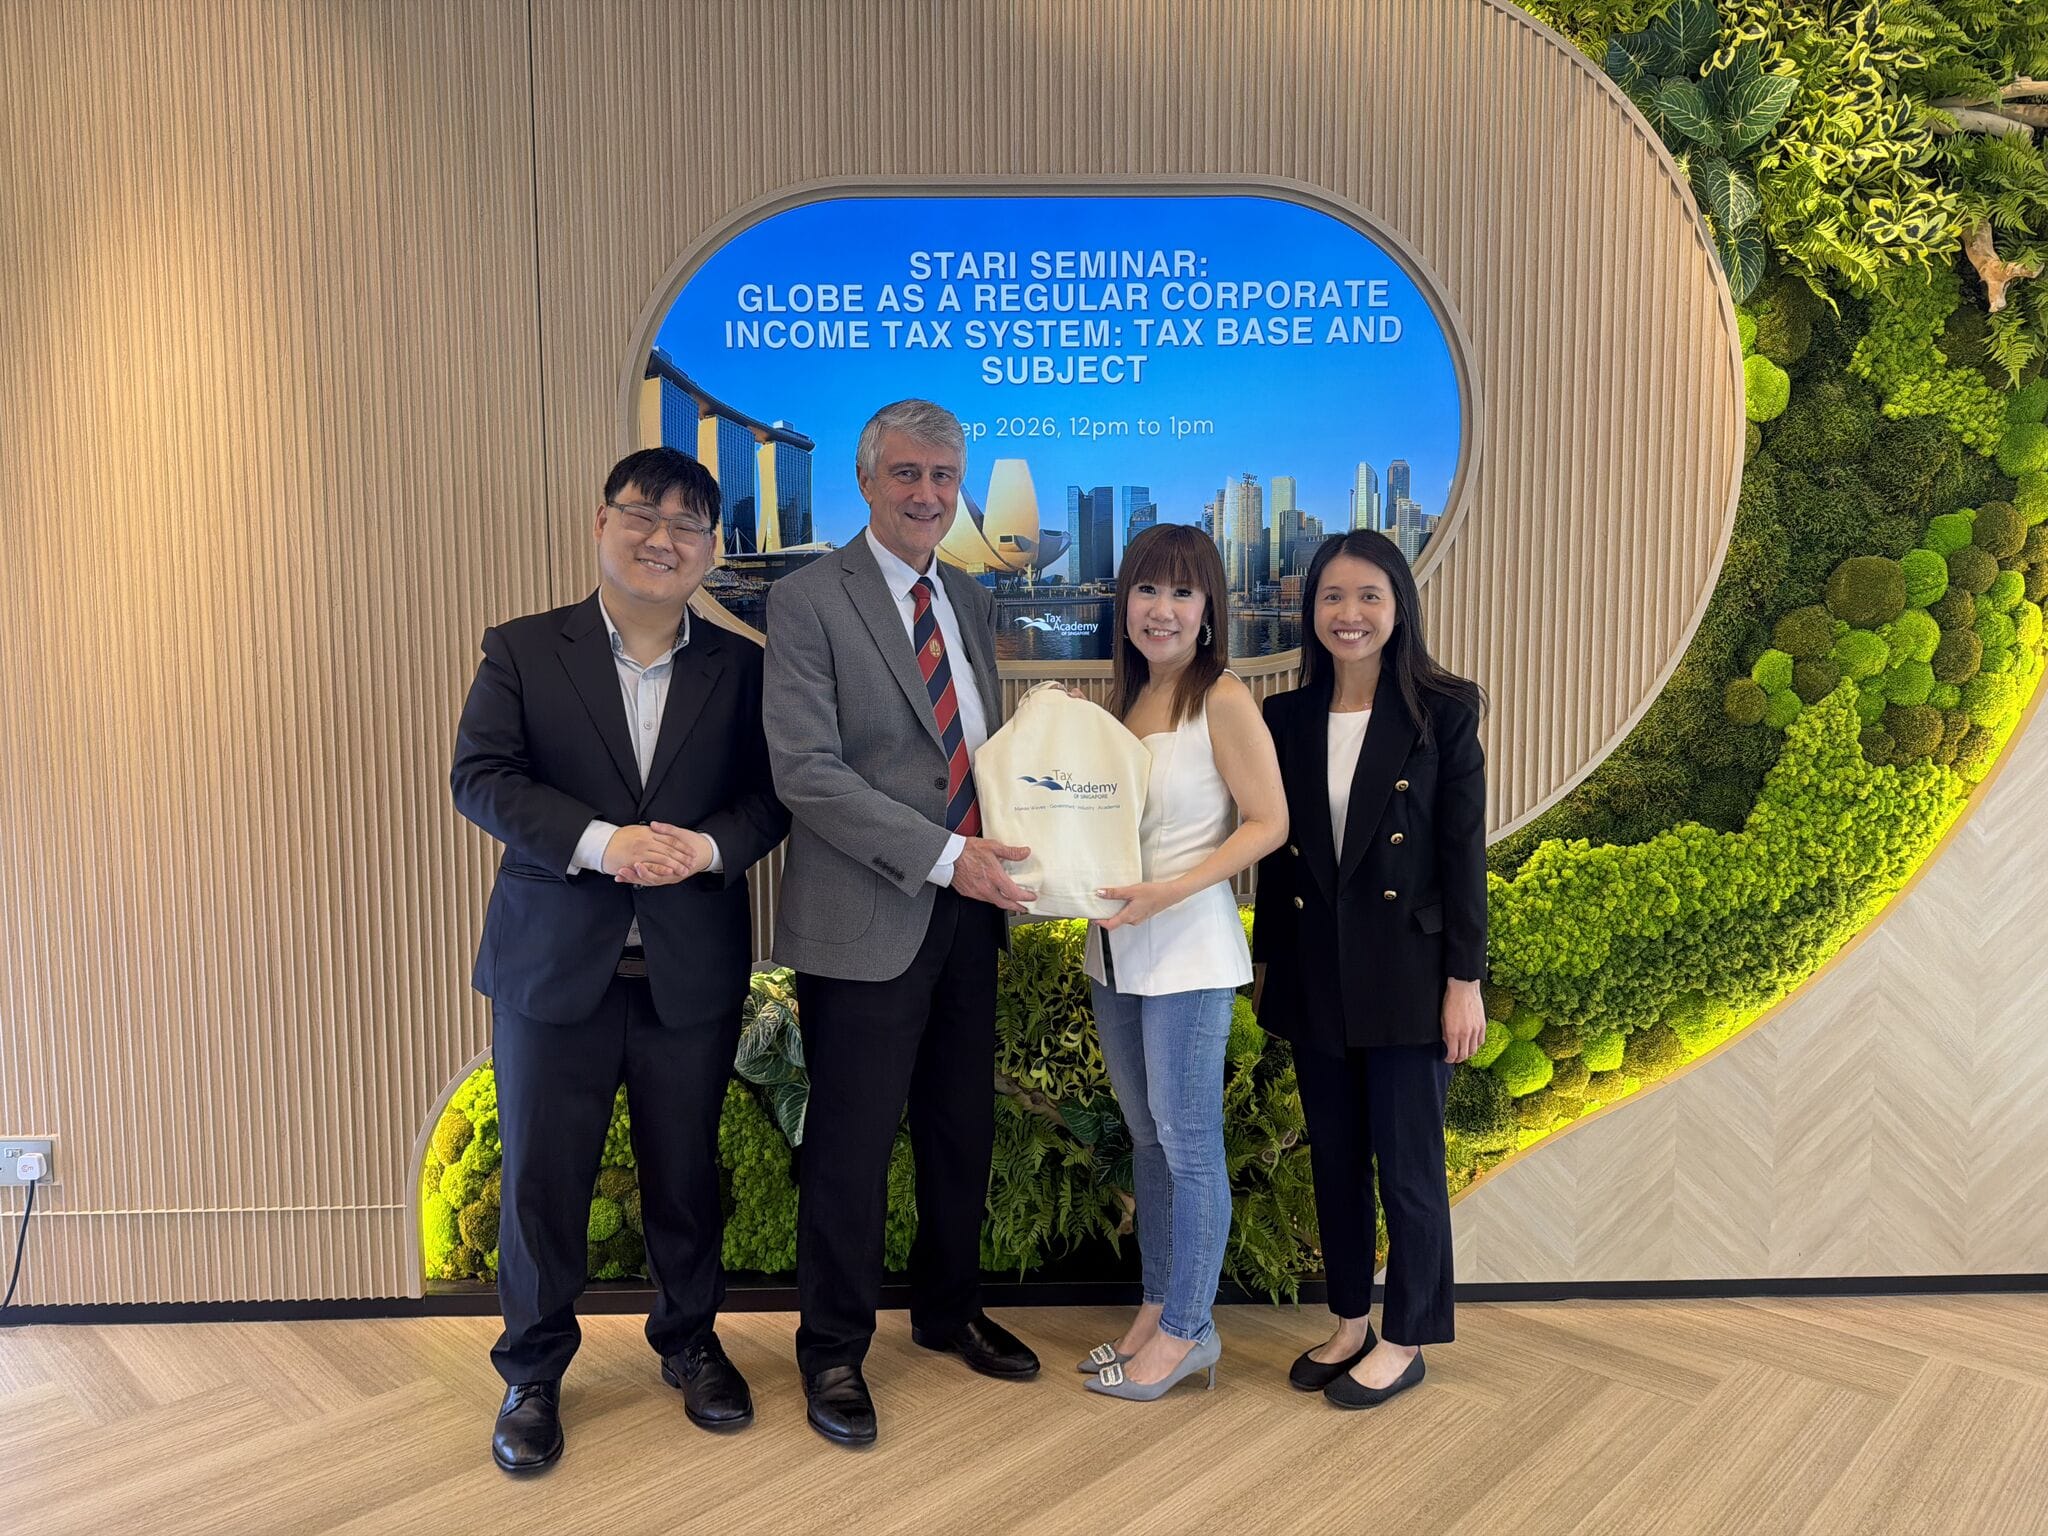
From left to right: Dr Vincent Ooi, Professor Peter Harris, Ms Eunice Toh, Ms Chua Jia Ying
Professor Peter Harris of the University of Cambridge explored this question at the Singapore Tax Academy Research Initiative (STARI) Seminar, GloBE as a Regular Corporate Income Tax System: Tax Base and Subject, held at the Tax Academy of Singapore Hub on 4 September 2026. Professor Harris is a member of the STARI Academic Expert Panel.
Moving beyond the conventional view of the Global Anti-Base Erosion (GloBE) Rules as part of the global minimum tax framework, Professor Harris examined their structure and operation through the lens of a conventional corporate income tax system.
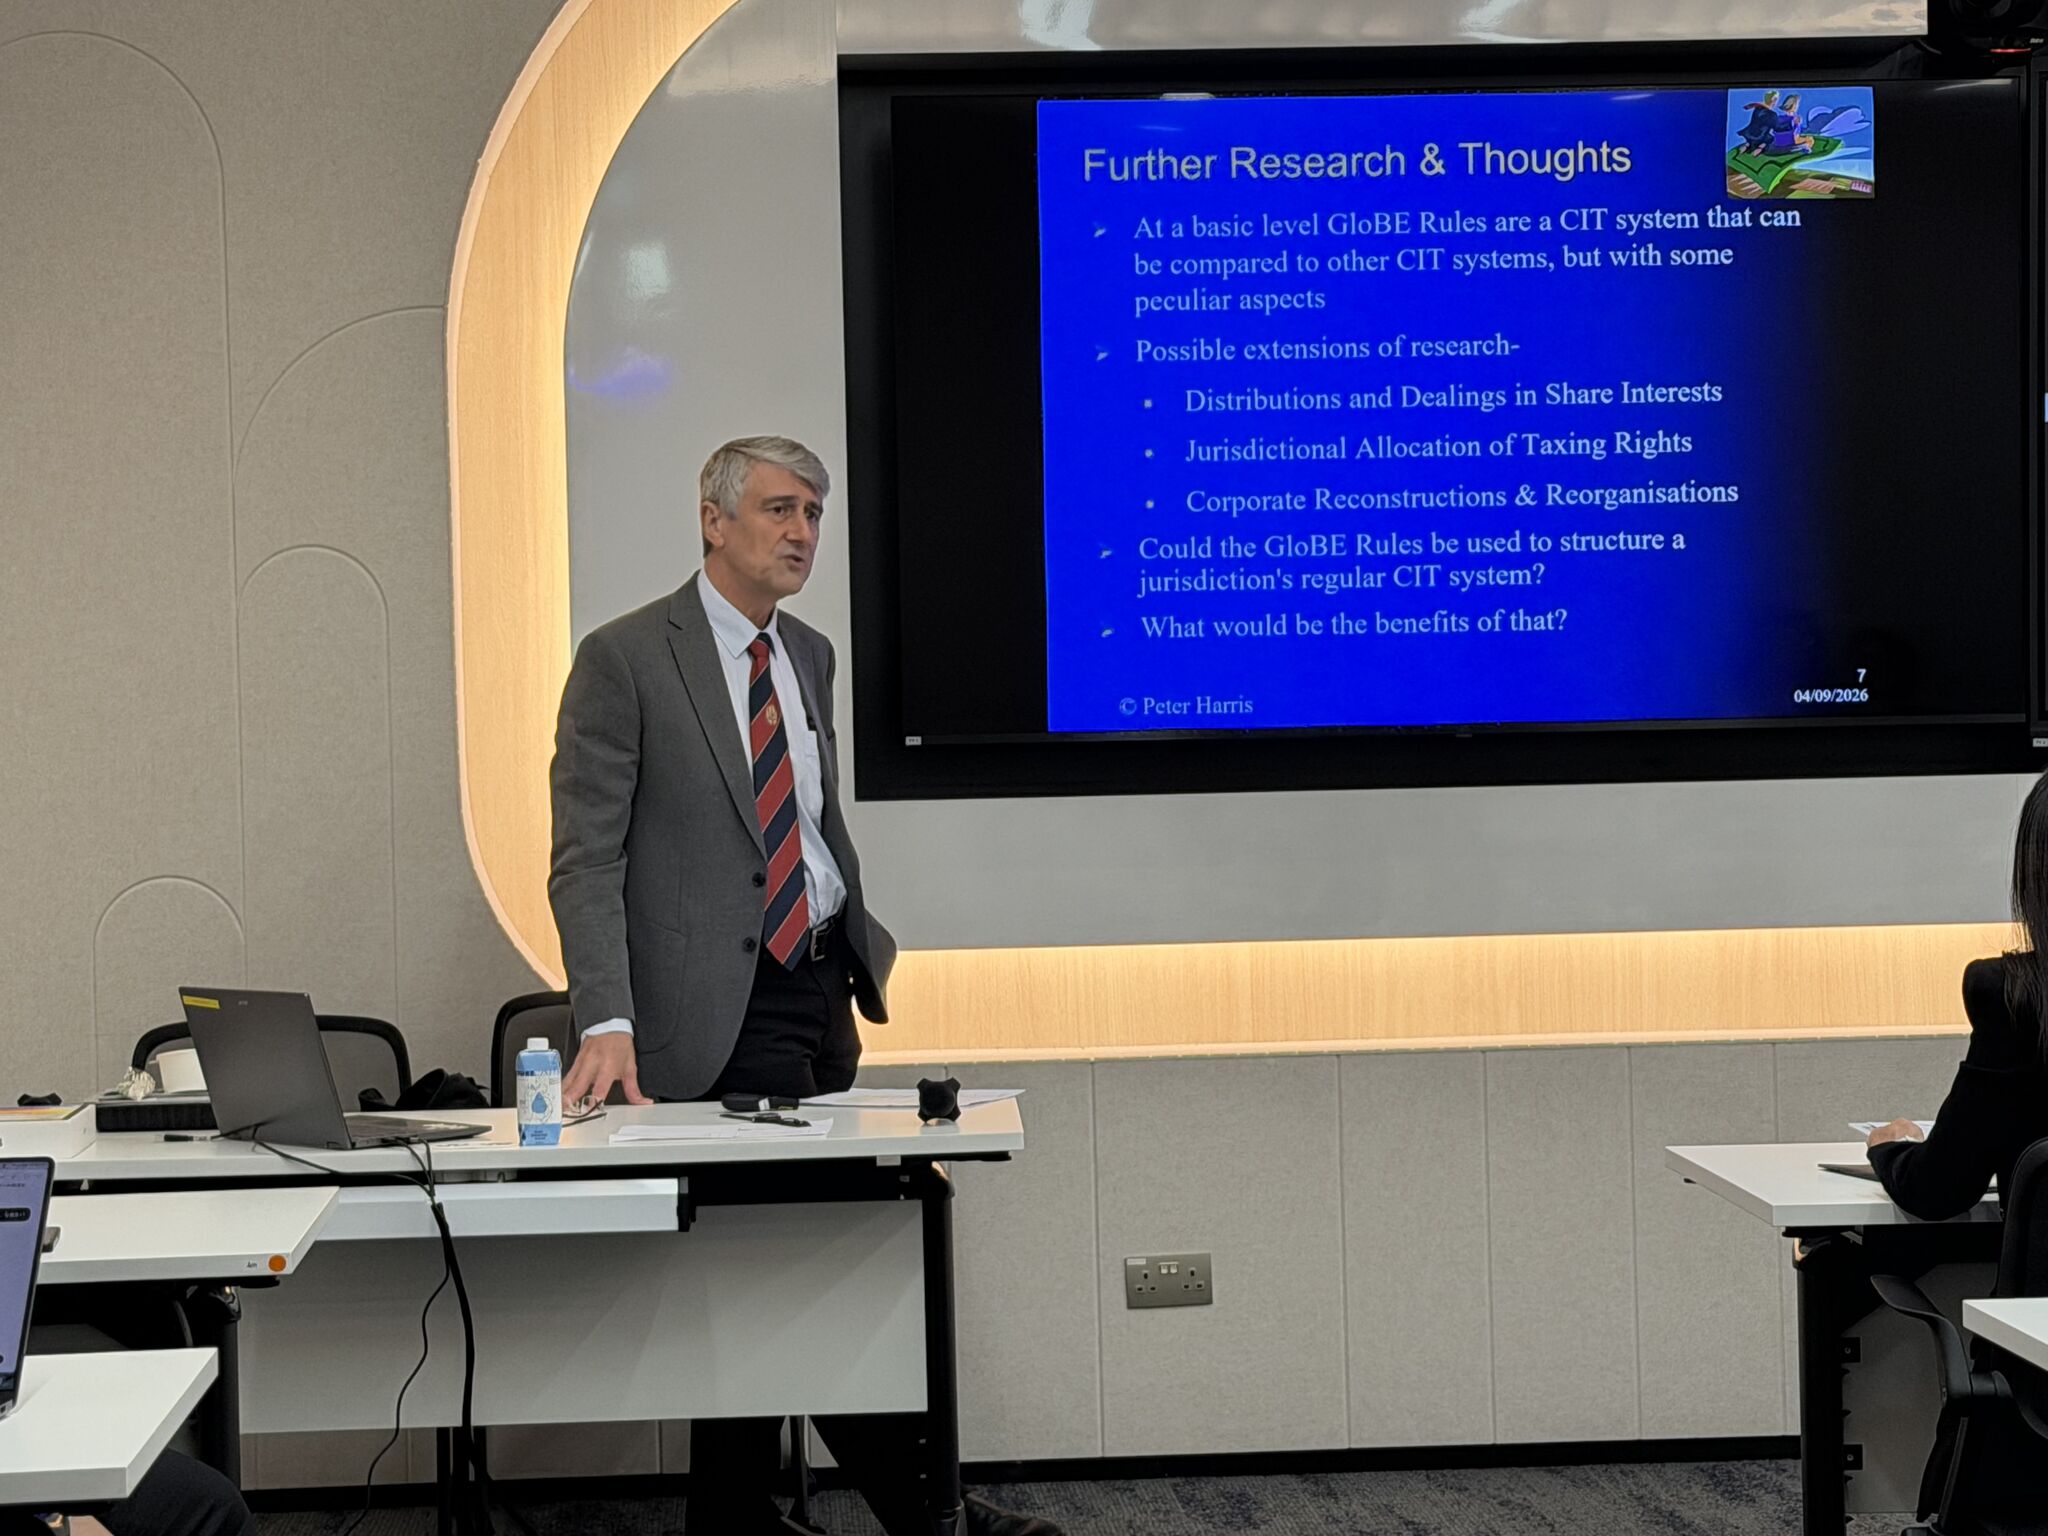
Professor Peter Harris conducting the STARI Lunchtime Seminar on GloBE as a Regular Corporate Income Tax System: Tax Base and Subject
Drawing on his 2024 book, Corporate Tax Law, he compared the GloBE Rules with corporate income tax systems in China, Germany, the United Kingdom and the United States. The seminar explored key areas including the determination of the tax base, treatment of losses and allocation of tax liability.
The comparative analysis offered fresh perspectives on where GloBE reflects established corporate income tax principles—and where it departs from them—highlighting the distinctive nature and complexity of the framework.
Through STARI, Tax Academy connects leading academics, government officials and practitioners to examine emerging tax issues and contribute to informed dialogue on the future of taxation.