When Working from Home Creates a Taxable Presence
11 September 2026
Could an employee working from home in another country create a taxable presence for the employer?
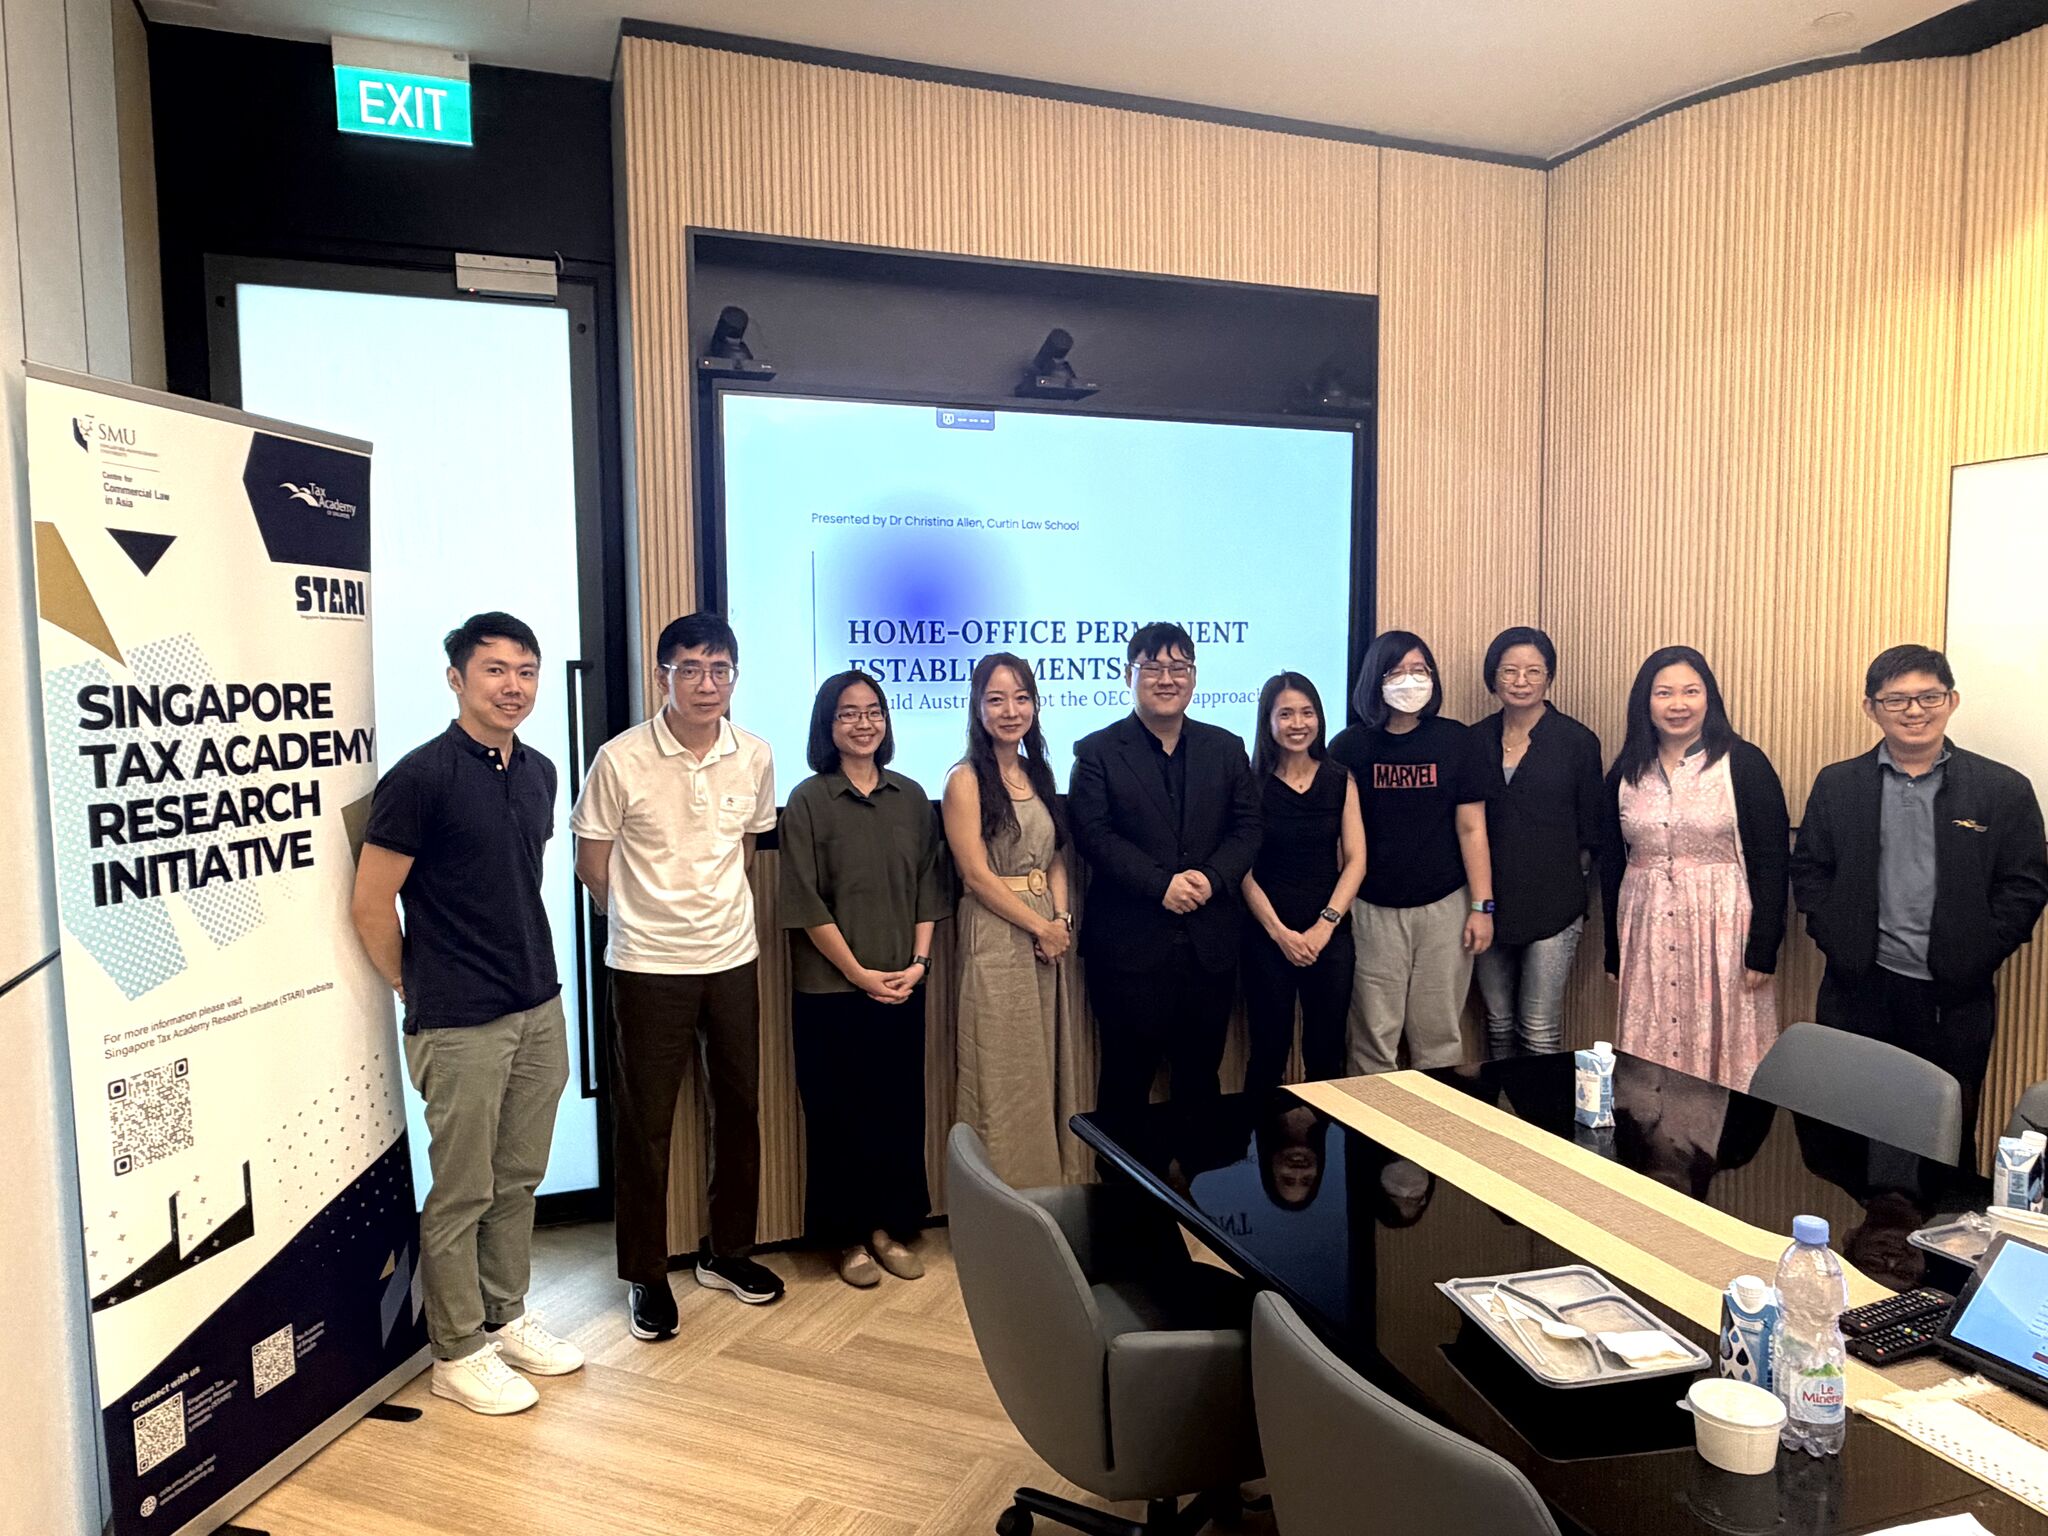
Dr Christina Allen with the Participants of the STARI Lunchtime Seminar - “Home-office” Permanent Establishments: An Australian Case Study
This increasingly important question was examined at the Singapore Tax Academy Research Initiative (STARI) Lunchtime Seminar, “Home-office” Permanent Establishments: An Australian Case Study, led by Dr Christina Allen.
Against the backdrop of the OECD’s 2025 Update to the OECD Model Tax Convention, the seminar explored how the rise of remote and cross-border working is reshaping the application of the permanent establishment (PE) concept.
Dr Christina Allen conducting the STARI Lunchtime Seminar
Using Australia as a case study, Dr Allen examined the significance of the 50% working-time threshold and the wider commercial circumstances that may cause a home office to constitute a PE. The discussion also considered the interaction with domestic law, tax treaties, withholding tax obligations and the attribution of profits.
The seminar highlighted how flexible working arrangements are testing established international tax principles and creating new compliance and risk considerations for businesses operating across borders.
International tax does not stand still. As businesses become more global and working arrangements more flexible, long-standing tax concepts must continually be tested and re-examined. Through STARI, Tax Academy provides a platform for academics, policymakers and practitioners to explore these developments and their practical implications for businesses and tax professionals.
Dr Vincent Ooi presenting the token of appreciation to Dr Christina Allen