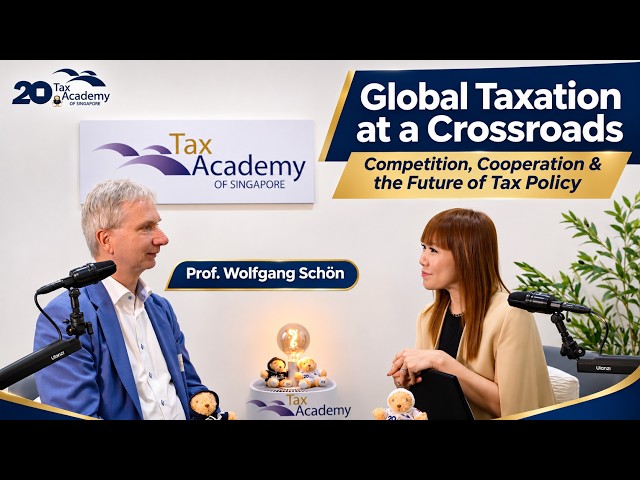
Global Taxation at a Crossroads: Competition, Cooperation & Tax Policy | Prof. Wolfgang Schön
6 November 2026
A concise summary of the main points regarding this article.
Can countries remain competitive while working towards a more coordinated international tax system?
Professor Wolfgang Schön, Director of the Max Planck Institute for Tax Law and Public Finance in Munich, joins the Tax Academy of Singapore to explore the evolving landscape of global taxation, from the future of OECD Pillar One and Pillar Two to the growing tension between tax competition and international cooperation.
Drawing on decades of experience in international tax law and policy, Professor Schön discusses the implications of increasingly fragmented tax rules for multinational businesses, the importance of legal certainty, and how smaller open economies such as Singapore can remain competitive in a changing global environment.
International taxation at a turning point
International taxation has undergone significant changes over the past decade.
Initiatives such as the OECD's Base Erosion and Profit Shifting (BEPS) project and the Two-Pillar Solution have sought to address longstanding challenges in taxing multinational enterprises and coordinating national tax systems.
Yet the pursuit of international consensus has also revealed fundamental tensions.
Countries continue to compete for investment, protect their national interests and respond to changing economic circumstances. Meanwhile, businesses face an increasingly complex landscape of international rules, domestic measures and geopolitical uncertainty.
In this conversation with Tax Academy of Singapore, Professor Wolfgang Schön reflects on whether international tax reforms have achieved their intended objectives — and what a more practical and resilient approach to global tax cooperation might look like.
Five perspectives from Professor Wolfgang Schön
1. International tax reform: Progress under Pillar Two, uncertainty under Pillar One
Has the international community made meaningful progress towards a more coherent tax system?
For Professor Schön, the answer is both yes and no.
He distinguishes between the progress achieved under the OECD's two pillars.
Pillar Two, which seeks to establish a coordinated minimum level of taxation for large multinational enterprises, has achieved considerable momentum. Its implementation through European Union legislation and adoption by other jurisdictions represents a significant development in international tax cooperation.
Professor Schön also points to the agreement on a side-by-side approach involving the United States as an indication that different national approaches to minimum taxation may coexist within a broader framework.
Pillar One, however, presents a contrasting picture.
Originally intended to reallocate certain taxing rights to market jurisdictions, Pillar One Amount A has encountered substantial difficulties in achieving the international agreement necessary for implementation.
In Professor Schön's assessment, its prospects remain uncertain, even as the underlying demand for market-country taxation continues to evolve.
He also highlights the increasing involvement of the United Nations in international taxation, suggesting that alternative forums for cooperation may become more influential, although their eventual outcomes remain unclear.
Together, these developments suggest that international tax coordination is progressing unevenly, rather than through a single, universally accepted framework.
2. Market-country taxation is advancing — with or without Pillar One
One of Professor Schön's central observations is that market-country taxation has continued developing even without a comprehensive multilateral agreement under Pillar One.
While international attention has focused heavily on the OECD's negotiations, many jurisdictions have independently introduced measures seeking to tax economic activities connected to their domestic markets.
These include digital services taxes and increased taxation of certain cross-border royalty and service payments.
Professor Schön also draws attention to the broader relationship between tariffs and the taxation of cross-border economic activity.
The result is an increasingly fragmented landscape in which different jurisdictions pursue market-country taxation through different legal and policy instruments.
This presents an important challenge.
Although market jurisdictions may share an interest in taxing economic activity connected to their economies, unilateral approaches can create overlapping taxing claims, uncertainty and additional complexity for international businesses.
For Professor Schön, the central question is no longer simply whether market-country taxation will expand.
It is how governments can coordinate these developments to establish a more predictable and workable international environment.
3. Tax competition and cooperation need not be mutually exclusive
Countries naturally seek to attract investment and maintain their economic competitiveness.
At the same time, growing cross-border economic integration creates pressure for greater coordination over tax rules and standards.
Can these objectives coexist?
Professor Schön argues that international cooperation requires flexibility rather than an expectation that every country will accept identical, universally binding rules.
He highlights the importance of what economists call incentive compatibility — the principle that countries are more likely to participate in cooperative arrangements when doing so aligns with their own interests.
As he explains:
Countries need to see that coordination is in line with their own interests.— Professor Wolfgang Schön
International organisations, including the OECD and United Nations, have long facilitated cooperation through common approaches, model frameworks and other coordinating mechanisms.
Professor Schön sees continued value in these arrangements, particularly where they allow countries to cooperate without requiring complete uniformity.
The challenge for policymakers is therefore to develop frameworks that recognise different national interests while providing enough coordination to reduce unnecessary conflicts.
Cooperation, in this view, does not require the elimination of competition. It requires rules and institutions capable of accommodating both.
4. For businesses, legal certainty matters more than where taxes are paid
From a business perspective, the growing complexity of international taxation raises a practical concern: are reforms creating greater certainty, or simply adding further compliance obligations?
Professor Schön observes that businesses consistently place significant importance on two issues: legal certainty and the avoidance of double taxation.
In his experience, multinational businesses are often less concerned about precisely which jurisdiction collects a tax than about knowing their obligations and ensuring that the same income is not taxed repeatedly.
They want to pay the appropriate tax, at the appropriate time, under clear and predictable rules — without facing unexpected disputes later.
However, achieving this certainty is becoming increasingly challenging.
Existing anti-avoidance measures introduced through the BEPS project now interact with the extensive requirements of Pillar Two, creating substantial implementation demands for both businesses and tax administrations.
Whether these reforms will eventually produce a more stable international tax environment remains an open question.
Professor Schön suggests that the international system may ultimately reach a point of relative stability, but further uncertainty cannot be ruled out.
For businesses operating across multiple jurisdictions, predictability and administrative practicality remain essential considerations when evaluating the success of international tax reform.
5. Singapore's competitiveness goes beyond tax incentives
What do these developments mean for smaller open economies such as Singapore?
As international tax coordination increases, countries may face greater constraints on the use of certain tax incentives to attract foreign investment.
However, Professor Schön emphasises that taxation is rarely the primary consideration when businesses decide where to invest or establish operations.
As he observes:
Tax is not number one. It's number five or number seven.— Professor Wolfgang Schön
Investment decisions are shaped by a much wider set of factors, including the business environment, legal institutions and the practical conditions under which companies operate.
For Singapore, Professor Schön highlights several important strengths.
These include the rule of law, legal certainty and a tax administration that is responsive to business needs.
Such institutional qualities can support an attractive investment environment even as international tax rules become more coordinated.
His observations point to a broader lesson for policymakers: national competitiveness cannot be reduced to headline tax rates or financial incentives alone.
A stable, predictable and well-administered tax system can itself be an important competitive advantage.
The future of tax cooperation: Flexibility in a fragmented world
Looking ahead, Professor Schön returns to what he considers a pressing challenge for international taxation: the growing fragmentation of market-country tax measures.
Digital services taxes, tariffs and other national approaches are developing along different trajectories, often without a sufficiently coordinated international framework.
In an era of geopolitical uncertainty, achieving universal agreement on every aspect of international taxation may be increasingly unrealistic.
Rather than relying entirely on comprehensive agreements requiring all countries to participate on identical terms, Professor Schön encourages policymakers to pursue common standards that are flexible and resilient.
Such frameworks should continue functioning even when individual countries depart from an established consensus.
The objective is not necessarily complete uniformity, but a level of cooperation capable of accommodating changing national priorities without undermining the international system as a whole.
His central message is particularly relevant for policymakers, tax administrations and multinational businesses navigating today's international tax environment.
The future of international taxation may depend less on achieving perfect global agreement, and more on developing practical forms of cooperation that can endure despite disagreement.
About Professor Wolfgang Schön
Professor Dr. Dr. h.c. Wolfgang Schön is Director of the Max Planck Institute for Tax Law and Public Finance in Munich, Germany, and an Honorary Professor at Ludwig-Maximilians-Universität Munich.
A leading scholar in international and corporate tax law, his research spans taxation, corporate law, international economic relations and the interaction between legal institutions and public policy.
Professor Schön has held senior academic positions at the Universities of Bielefeld and Bonn and has served as Vice President of the Max Planck Society and the German Research Foundation.
He has also contributed extensively to international tax scholarship and policy discussions through his involvement with academic institutions and professional organisations worldwide.
During his visit to Singapore in October 2026, Professor Schön delivered the keynote address, Market Country Taxation after Pillar One, at the IFA–TA International Tax Conference 2026, examining the future of market-country taxation amid uncertainty surrounding international tax coordination.
Explore further
Read more about the IFA–TA International Tax Conference 2026
Explore key discussions on market-country taxation, international tax nexus, global minimum taxation and the evolving relationship between national taxing rights and international coordination.
Discover more podcast conversations
The Tax Academy of Singapore Podcast brings together policymakers, academics, practitioners and tax leaders to explore the ideas shaping tax in Singapore, Asia and beyond.